
.
Latest disruption highlights how a failure in one digital channel can quickly affect consumers, businesses and everyday payments
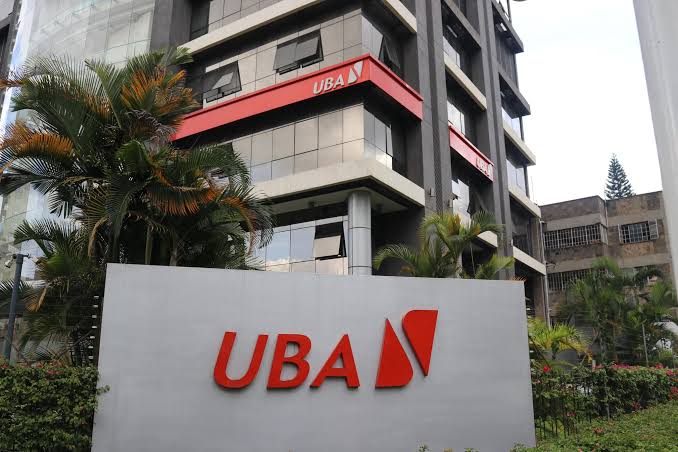
Nigeria’s growing dependence on mobile banking is coming under fresh scrutiny following a service disruption that affected customers of United Bank for Africa (UBA), highlighting the risks that accompany the country’s rapid transition from traditional banking to digital financial services.
UBA apologised to customers on September 2 after users reported difficulties accessing its mobile banking application. The bank said it was working to restore normal service and advised affected customers to use alternative banking channels.
While the incident was limited to a bank’s digital platform, its wider significance goes beyond an unavailable mobile application. For millions of Nigerians who now rely on smartphones to transfer money, pay bills, receive payments and manage business transactions, a digital banking outage can quickly become an economic disruption.
Mobile banking is now critical infrastructure
Nigeria’s financial system has undergone a major digital transformation over the past decade.
Mobile applications, USSD services, internet banking, fintech platforms and instant bank transfers have increasingly replaced cash and physical branch visits for everyday transactions.
That convenience, however, has created a new dependency.
When a banking application fails, customers may be unable to access funds even when money remains available in their accounts. For businesses, the consequences can be more serious, particularly where payments, supplier transfers, salaries or customer collections depend on real-time digital transactions.
The BusinessDay report noted that banking disruptions can extend beyond an application itself when the underlying banking infrastructure is affected.
In such cases, problems can potentially spread across several customer-facing services, including transfers and payments.
Nigeria has seen bigger banking disruptions
The latest UBA incident is not an isolated occurrence.
In October 2024, customers of GTBank and Zenith Bank experienced prolonged service difficulties as the lenders migrated to new core banking platforms. Customers reported problems accessing services and completing transactions, while businesses also faced operational delays.
The episodes demonstrated an important distinction between an ordinary app malfunction and a disruption linked to a bank’s core infrastructure.
A mobile banking application is only the visible layer of a much larger technology architecture. Behind it are core banking platforms, payment switches, databases, cybersecurity systems, telecommunications networks and other infrastructure that must operate continuously.
When one of these critical components fails, the disruption can affect several services simultaneously.
The NIBSS factor
Nigeria’s wider payment ecosystem adds another layer of dependency.
The Nigeria Inter-Bank Settlement System (NIBSS) operates the infrastructure supporting instant electronic transfers between banks and financial institutions. Its importance was underscored by disruptions in 2026 that affected transfers, wallet funding and fintech services.
Industry observers have compared NIBSS to an invisible backbone of Nigeria’s digital financial system because millions of transactions across banks, fintech platforms and payment channels depend on interconnected infrastructure.
As one analyst told BusinessDay during an earlier disruption, “When it is down, no transfer successfully goes through in Nigeria.”
That vulnerability matters because Nigeria’s digital economy is increasingly interconnected. A customer may use a bank application to fund a fintech wallet, transfer money to another bank, pay a merchant through a payment processor or receive a business payment through a digital platform.
A failure at one point in that chain can therefore have consequences beyond the original institution.
Businesses face the bigger risk
For individuals, an outage can mean an unsuccessful transfer or temporary difficulty accessing an account.
For businesses, the cost can be significantly higher.
A merchant waiting for customer payments may struggle to confirm transactions. An online seller may be unable to receive or verify transfers. Companies relying on digital banking for supplier payments may face delays, while employees could experience problems receiving salary-related transactions.
This makes digital resilience increasingly important for Nigerian businesses.
Companies cannot assume that a single payment channel will always be available. Maintaining appropriate alternative channels and clear procedures for verifying transactions during outages is becoming part of modern financial risk management.
What customers need to know
Customers should also understand that a failed transaction does not necessarily mean money has been permanently lost.
During system disruptions, transactions can sometimes remain pending or take time to reconcile. Customers should therefore avoid repeatedly initiating the same payment simply because an earlier transaction has not immediately reflected, as this could create duplicate transactions once systems recover.
Banks, for their part, need to provide timely communication when disruptions occur, clearly explaining what services are affected and which alternative channels customers can safely use.
Digital convenience must come with resilience
Nigeria’s transition toward cashless and mobile-first banking is unlikely to reverse.
The benefits are substantial: faster transactions, greater accessibility, lower dependence on physical branches and broader participation in the digital economy.
But the more Nigerians depend on digital banking, the more important resilience becomes.
The latest UBA disruption therefore offers a broader lesson for the financial sector: digital banking is no longer simply a convenience; it is increasingly part of the country’s critical economic infrastructure.
Banks, fintech companies, payment operators and regulators will need to ensure that investments in digital services are matched by stronger backup systems, reliable infrastructure, cybersecurity, rapid recovery mechanisms and transparent customer communication.
As Nigeria deepens its digital financial economy, the real test will not be whether outages can be eliminated entirely. It will be whether the system can absorb them without bringing everyday economic activity to a standstill.